How to Handle Your Venmo Transactions
A client pulled up her spending report last month and told me her dining number was wrong. Monarch said she’d spent about $600 eating out. She was sure it was closer to $300.
She was right. She was also the one who’d doubled it.
Her habit — a good one — is to put group dinners on her card and let friends Venmo her, or to Venmo a friend who grabbed the check. Every one of those payments was landing in her budget twice. Not because the app was broken, but because Venmo is a middleman, and middlemen leave two sets of footprints.
Why Venmo shows up twice
Venmo doesn’t hold your money like a bank does. When you pay a friend $30, Venmo pulls $30 from your checking account and passes it along. Your budgeting app, if it’s connected to both, sees two things:
In Venmo: a $30 payment to your friend. That’s the real spending — it’s the line that knows what the money was for.
In checking: a $30 charge from “Venmo.” That’s the money leaving your bank on its way to Venmo. It knows where the money came from, not what you bought.
Categorize both as dining and you’ve spent $60 on a $30 meal. Do that a few dozen times a year and your spending data stops being something you can trust — which is the moment most people quietly stop looking at it.
The most underrated category in your budget
Every decent budgeting app has a category called Transfer. It means money moving between two accounts you own. Checking to savings. Your bank to your credit card. Your bank to Venmo.
Transfers don’t count as spending and don’t count as income, because nothing actually left your household. The money changed rooms; it didn’t leave the house.
That’s exactly what the checking-side “Venmo” charge is. So the fix is one rule:
The Venmo account gets the real category. The bank account gets Transfer.
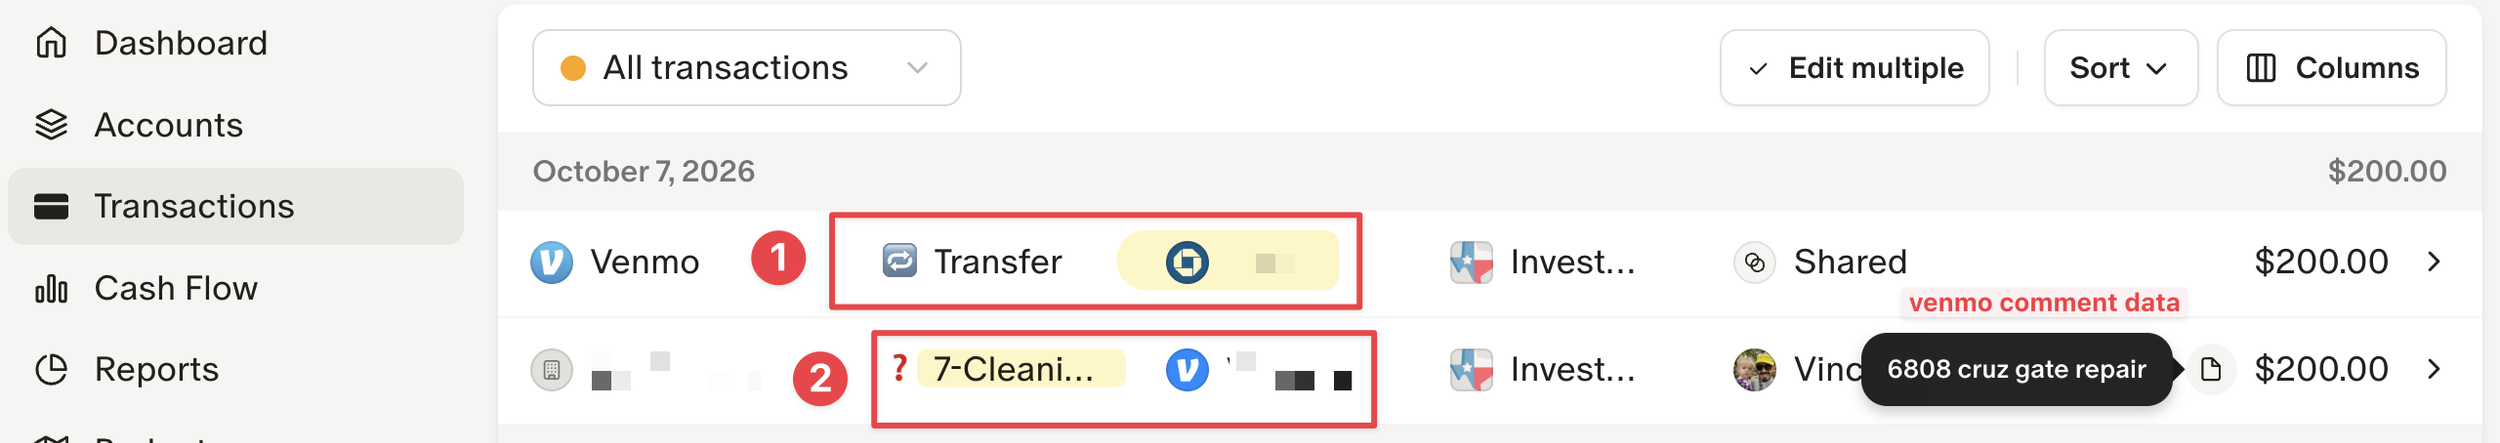
1 - The money leaving your bank account
2 - Venmo transaction, which provides who you paid and Venmo comment data. Use the comment data to correctly categorize what you paid for.
The $30 counts once, as dining, in the account that knows it was dinner. The $30 bank charge drops out of your reports entirely. Your dining number goes back to being true.
Setting it up (about ten minutes, once)
I’ll describe this in Monarch, which is what we use with clients, but the logic is the same in any app that lets you connect Venmo.
1. Connect Venmo as an account. The whole approach depends on the app seeing the Venmo side. Add it the same way you’d add a bank, and give it an obvious name.
2. Categorize the Venmo-side payments with whatever you actually paid for — dining, rent, your share of the cabin. Add a short note while you’re there. Venmo memos are emojis; a month from now “🍕” won’t tell you anything.
3. Mark the bank-side “Venmo” charges as Transfer. Then make it permanent: create a rule that says if the merchant contains “Venmo” and the account is my checking, set the category to Transfer. That one rule means you never have to think about this again.
When friends pay you back
This is the part the $600-dining client was missing, and it works the same way in reverse.
Say you put a $120 dinner on your card and three friends send you $30 each. Leave the $120 card charge as dining. Then categorize the three incoming $30 Venmo payments as dining too — because they’re money in, they offset the charge, and your dining total lands at $30. That’s what dinner actually cost you. When you move the $90 from Venmo to your bank, that’s a transfer.
If the money coming in is real income — someone paying you for work, selling an old bike — it gets an income category instead. The transfer at the end is the same either way.
Two habits that keep it clean
Keep your Venmo balance at zero. Money sitting in Venmo isn’t earning anything and isn’t doing anything for your plan. Cash out when money comes in. Also, when you transfer money paid to you into your bank account, transfer the exact amount for the specific transaction so you can match it correctly. Otherwise, you'll have a large amount to split, which will be a real pain in the butt and really confusing.
Don’t half-connect. If you decide not to connect Venmo at all, the rule flips: the bank-side charge becomes the expense, and you’ll want notes on every one. That works fine. What doesn’t work is doing both — some payments connected, some not — because you’ll end up with some counted twice and some not at all.
Your small victory this week: open your budgeting app, search your checking account for “Venmo,” and check what category those charges are sitting in. If they’re anything other than Transfer, you’ve just found some fake spending.
💡 Quick thought: A budget doesn’t have to be perfect to be useful. It has to be trusted. Double counting is how trust leaks out.
On Monarch: Monarch is a budgeting app we use with clients to connect accounts and track spending. Small Victories Wealth receives no compensation from Monarch — no referral fees, no affiliate arrangement, no revenue share. Clients in our ongoing planning services get Monarch access as part of their fee; for our budget packages and Budget Support, you keep your own Monarch subscription. It’s one tool among several, and it may not be the right fit for every situation.
